5 Reasons You May Be Ready to Retire Even If Your Money Is Still Growing
Many people delay retirement because their finances are still improving. The portfolio is growing, the paycheck is strong, and another year of work seems like an easy way to create even more security. From a purely financial perspective, continuing to work can look like the obvious choice.
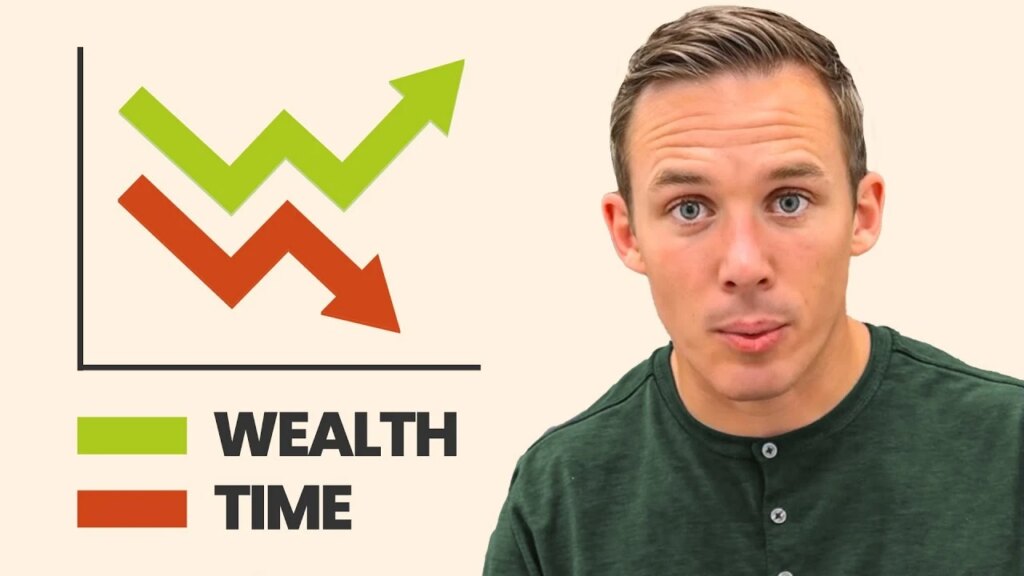
But retirement is not only a financial decision. Wealth also includes time, health, mental well-being, and relationships, and those resources do not always improve simply because your net worth does. At some point, working longer can increase financial wealth while quietly reducing the other forms of wealth that make retirement worth having.
1. Your Time May Be More Valuable Than the Extra Money
Time wealth is one of the easiest resources to underestimate because it does not appear on a balance sheet. Every year of work adds income and potentially increases retirement savings, but it also uses another year that can never be earned back. The older you get, the more important that trade becomes.
Someone who already has enough money to support retirement may gain relatively little from another year of financial accumulation compared with what they give up in time. That year might have been spent traveling, helping family, seeing grandchildren, pursuing hobbies, or simply living at a slower pace. Those experiences can be postponed, but they cannot always be recreated later.
The problem is that money provides immediate feedback while time does not. You can watch an investment account rise every month and see the reward for staying employed. There is no monthly statement showing how many healthy holidays, family dinners, or active years remain.
That is why retirement planning should ask more than whether another year of work improves the financial forecast. It should also ask whether the improvement is meaningful enough to justify spending another year of a finite life earning it.
2. Good Health Is Part of Your Retirement Wealth
Financial independence has much less value if poor health prevents you from enjoying it. Retirement plans often assume that people will travel, exercise, spend time outdoors, or take on projects they have postponed for years. Those plans depend on having enough physical ability to actually do them.
Health can also deteriorate gradually. Someone may feel capable of working another five or 10 years and assume the same energy will be available afterward, but there is no guarantee that will be true. A person who waits until every financial variable is perfectly optimized may discover that the physical window for enjoying retirement has narrowed.
This does not mean everyone should retire at the first sign of fatigue. Work can provide structure, purpose, movement, and social interaction that support health. The question is whether your specific job is adding to your well-being or steadily taking away from it.
If work stress, long hours, commuting, or constant demands are interfering with sleep, exercise, or medical care, the financial benefit of staying employed may be accompanied by a health cost. That cost deserves to be part of the retirement calculation.
3. Mental Well-Being Can Matter More Than Another Year of Savings
Retirement can also become attractive when work is causing persistent stress or anxiety. A strong salary does not automatically compensate for feeling overwhelmed, exhausted, or mentally unavailable outside the office. Financial security is supposed to create freedom, not simply make it easier to tolerate a life that no longer feels sustainable.
For some people, leaving work can provide mental space that has been missing for years. The absence of deadlines, constant communication, and professional pressure can create room for rest, reflection, and new routines. That emotional relief can be valuable even if it cannot be assigned a dollar amount.
Retirement does not automatically improve mental health, of course. People who rely heavily on work for identity and purpose can struggle after leaving. The better approach is to ask what retirement will replace work with rather than assuming that simply stopping will solve everything.
If someone already has interests, relationships, routines, and goals outside the job, retirement may create more room for those parts of life to grow. In that case, leaving work can represent a shift toward better mental balance rather than an escape from responsibility.
4. Relationships Need Time Before Retirement Too
Social wealth is built through time, attention, and repeated interaction. Strong relationships with a spouse, children, grandchildren, friends, and community do not appear automatically when someone retires. They are usually the result of years of investment.
This is one of the biggest risks of delaying retirement too long. Someone can spend decades prioritizing work with the assumption that relationships will receive more attention later. By the time later arrives, children may have moved, friendships may have faded, or a spouse may have developed different routines.
Retirement can create more time for relationships, but time alone does not guarantee connection. If those relationships have been neglected for years, they may require rebuilding. That is why social readiness should be considered before the retirement date rather than after it.
A person who already has meaningful relationships outside work may be better prepared for retirement than someone with a larger portfolio but very little social life beyond colleagues. Financial wealth can support retirement, but social wealth often determines whether retirement feels full or empty.
5. Your Financial Plan May Already Be Strong Enough
The final reason to retire early is the most obvious but also the one many people struggle to accept: you may already have enough. If expected income, savings, Social Security, pensions, and investments can reasonably support your lifestyle, continuing to work may no longer be necessary for financial security.
That does not mean the portfolio will stop growing or that another year of work would not make the plan stronger. It simply means the improvement may no longer be necessary to achieve the life you want. There is a difference between making a plan safer and making a plan meaningfully better.
This is where financial planning can provide clarity. A retirement plan should show what happens under reasonable assumptions for spending, market returns, inflation, healthcare, and longevity. If the plan remains resilient across different scenarios, then the decision to keep working becomes more about personal preference than financial necessity.
Some people will still choose to work because they enjoy it, and that can be an excellent decision. Others may realize that continuing to accumulate money is no longer worth sacrificing time, health, or relationships. Both decisions can be financially responsible when they are made intentionally.
Retirement Readiness Is More Than a Number
People often talk about retirement as though there is one magic savings target that determines readiness. In reality, retirement is a combination of financial, physical, emotional, social, and time considerations. A person can be financially prepared and personally unprepared, or personally ready while still needing more financial security.
The challenge is understanding which area is actually holding you back. If the answer is money, working longer may be necessary. If the finances are already strong but fear or habit is keeping you employed, the solution may have less to do with earning more and more to do with trusting the plan.
A holistic view forces the question to become broader. Instead of asking, “Can I retire?” ask, “What happens to every important part of my life if I continue working?” That can lead to a very different answer.
The Five Forms of Wealth Affect One Another
Financial wealth supports the other parts of life by providing security and choice. Good health allows you to use your time more fully, while strong relationships can improve emotional well-being. Time makes it possible to nurture all of those areas.
The problem comes when one form of wealth is pursued at the expense of all the others. Someone can maximize financial wealth while neglecting health, relationships, and personal time. The balance sheet improves while the overall quality of life becomes weaker.
Retirement planning works best when these forms of wealth are viewed together. The objective is not to maximize every category simultaneously, because that is rarely possible. It is to make sure one category is not consuming so much attention that the others are being permanently damaged.
Every Extra Year of Work Has a Trade-Off
Working longer is often presented as the safest financial option because it increases savings, delays withdrawals, and may increase future benefits. Those advantages are real. But the trade-off is also real.
Another year of work costs another year of personal time. It may also mean another year of stress, missed travel, delayed experiences, or less time with people who matter. The question is whether what you gain financially is worth what you give up elsewhere.
For someone who loves work, the trade may be easy to accept. For someone who is exhausted and financially secure, the same trade may make far less sense. Retirement planning becomes more useful when both sides are considered honestly.
Do Not Wait for Perfect Financial Certainty
One of the reasons people keep working is the hope that another year will eliminate uncertainty. The portfolio will be larger, the mortgage will be smaller, and retirement will feel safer. But financial uncertainty never disappears completely.
Markets can fall, healthcare expenses can rise, and life can change in ways no projection anticipates. The goal of retirement planning is not to create certainty but to create enough resilience that reasonable surprises can be absorbed.
If someone waits until there is no financial risk at all, retirement may never arrive. A strong plan should provide enough confidence to act even though the future remains uncertain.
Know What You Are Retiring To
Retirement works best when it creates room for something rather than simply removing work. That might be family, travel, volunteering, exercise, creative projects, part-time work, or a slower daily routine. The specific answer matters less than having one.
Someone who retires without a sense of purpose may discover that work provided more structure and identity than expected. That can make even a financially successful retirement feel unsatisfying. Preparing for retirement therefore includes thinking about daily life as carefully as investment withdrawals.
This is another reason social and mental wealth matter. A person with strong interests, relationships, and routines outside work is often better positioned to use retirement time well. Financial independence provides the freedom, but purpose determines what that freedom becomes.
Your Retirement Date Should Reflect Your Whole Life
There is no universally correct age to retire. Some people thrive by working into their 70s, while others are ready much earlier. The right answer depends on financial security, health, family, purpose, and personal priorities.
What matters is not allowing financial optimization to dominate every other consideration. Another $100,000 in the portfolio may be valuable, but so may another year with your spouse while both of you are healthy enough to travel. Those two forms of value cannot be compared perfectly, but they still need to be compared.
A retirement decision is ultimately an allocation decision. You are deciding how much more time to trade for money and how much money is enough to reclaim your time.
Enough Financial Wealth Should Eventually Buy Back Your Time
The entire purpose of saving for retirement is to reach a point where work becomes optional. If the financial plan already supports the life you want, continuing to accumulate may still be worthwhile, but it is no longer automatically necessary. That distinction matters.
Retirement is not about abandoning financial discipline. It is about using the security you created to support the rest of your life. Health, time, relationships, and emotional well-being all become more important as the years pass.
The best retirement decision is the one that recognizes all of those forms of wealth. If your finances are secure but another year of work is costing too much somewhere else, retiring earlier may not be financially irrational at all. It may simply mean you have decided that the most valuable things you own are no longer measured in dollars.
You should always consult a financial, tax, or legal professional familiar about your unique circumstances before making any financial decisions. This material is intended for educational purposes only. Nothing in this material constitutes a solicitation for the sale or purchase of any securities. Any mentioned rates of return are historical or hypothetical in nature and are not a guarantee of future returns.
Past performance does not guarantee future performance. Future returns may be lower or higher. Investments involve risk. Investment values will fluctuate with market conditions, and security positions, when sold, may be worth less or more than their original cost.