Why America’s Leaders Are Getting Older and What Happens When Power Finally Shifts
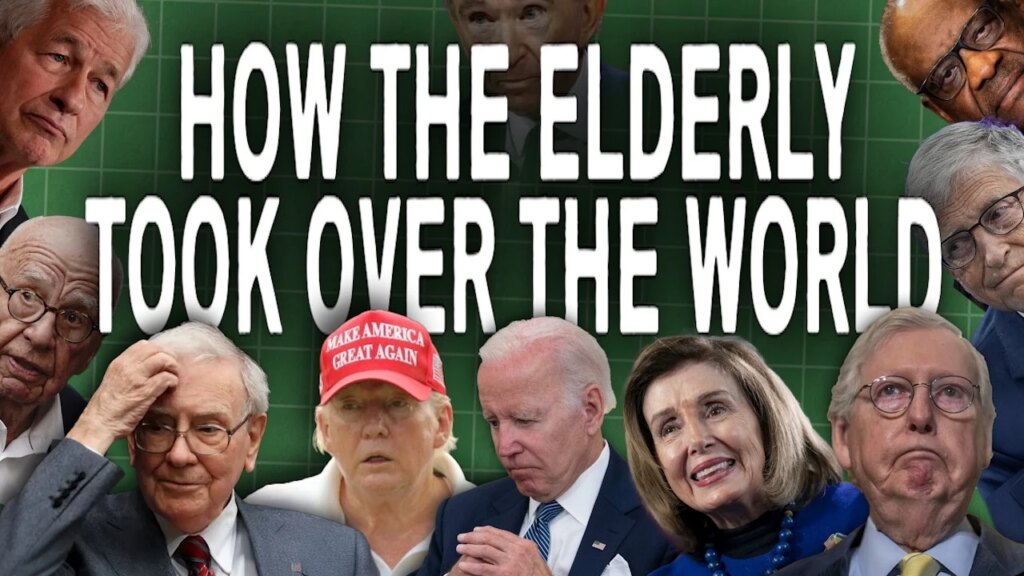
America’s most powerful institutions are older than many people realize. The average member of the House at the start of the 119th Congress was 57.9 years old, while the average senator was 63.9. Corporate leadership skews older too: a 2026 analysis of major companies found the average CEO in its sample was 59, with 42% age 60 or older.
That does not mean old age itself is a problem or that younger leaders are automatically better. Experience, institutional knowledge, and judgment can improve with age. The more interesting question is why political power, corporate authority, and wealth tend to accumulate in the same generations—and what happens when those generations eventually begin handing control to people who grew up under very different economic conditions.
Power Tends to Accumulate With Time
Very few people begin their careers with meaningful economic or political power. Executives usually spend decades moving through organizations before reaching the top, politicians build networks and seniority over repeated elections, and investors accumulate wealth gradually through earnings, homeownership, business ownership, and financial markets. Age therefore naturally correlates with influence.
Congress illustrates the pattern clearly. At the beginning of the 119th Congress, newly elected House members averaged 50.2 years old and newly elected senators averaged 55.1, considerably younger than the chambers overall. The institution becomes older partly because successful politicians remain in office for multiple terms.
Corporate America works similarly. Boards typically select CEOs from senior executives who already have decades of operating experience, and current leaders can remain in their positions for many years if companies perform well. That produces an executive class that is substantially older than the workforce it manages, even without any deliberate attempt to exclude younger people.
Baby Boomers Had Decades to Accumulate Assets
Baby boomers, generally defined as people born between 1946 and 1964, reached adulthood during a period of enormous economic and financial transformation. They participated in decades of rising home values, expanding stock ownership, employer retirement plans, globalization, and technological growth. Those conditions did not benefit every boomer equally, but they created significant opportunities for wealth accumulation among households able to buy homes and financial assets.
Federal Reserve data show how strongly wealth remains concentrated among older households. The 2025 Survey of Consumer Finances found that families age 75 and older experienced especially large wealth gains between 2022 and 2025, with median net worth rising 37%. By 2025, families in the oldest age group had higher net worth than households closer to traditional retirement age.
That does not mean age alone created the wealth. Income, education, race, homeownership, entrepreneurship, inheritance, and market participation all matter enormously. But older households have simply had more time to accumulate assets, benefit from compounding, and pay down debt.
Housing Played an Enormous Role
For many older Americans, housing became one of the most important sources of wealth. Buying property decades ago often meant purchasing at much lower nominal prices before years of appreciation increased home equity. The Federal Reserve reported that median net housing wealth among homeowners reached $230,000 in 2025.
That creates a generational divide because younger households are entering the housing market under very different conditions. Higher home prices and financing costs can make ownership harder to achieve, while existing owners benefit from the appreciation of an asset they already possess. The same price increase that strengthens one household’s balance sheet can make entry more difficult for another.
This dynamic can influence politics without requiring a coordinated effort by older homeowners. People generally support policies they believe protect their homes, neighborhoods, taxes, and quality of life. When older homeowners vote at higher rates and dominate local civic participation, their preferences can carry more weight in decisions over zoning, construction, transportation, and development.
Older Americans Participate More Reliably in Elections
Age differences in political participation are another reason older generations can exercise disproportionate influence. Census data from the 2024 presidential election show large turnout differences by age, with older adults substantially more likely to vote than the youngest eligible voters. Overall turnout among the citizen voting-age population was 65.3%.
That turnout gap matters beyond presidential elections. Local elections, zoning boards, school boards, and municipal races often attract far fewer voters than national contests, which can amplify the influence of groups that participate consistently. Older homeowners frequently have strong incentives to pay attention to property taxes, development, neighborhood character, and local services because those policies directly affect major assets and daily life.
This should not be interpreted as older voters illegitimately controlling government. They are using the political system available to everyone. The more important issue is that political influence reflects participation, and younger people who vote less consistently naturally have less impact on the policies being decided.
Wealth and Political Influence Reinforce Each Other
Money does not guarantee political power, but financial resources can make participation easier. Wealthier households often have more time, education, social connections, and access to institutions that allow them to engage with government. They can donate to campaigns, attend meetings, hire attorneys, organize neighborhood groups, or advocate for policies affecting businesses and property.
Age amplifies that effect because wealth tends to rise over much of the life cycle. Older households that accumulated homes, stocks, businesses, and retirement assets enter political debates with more at stake financially and more resources available to defend those interests. That can produce policies that appear tilted toward people who already own assets even when the process is driven by ordinary political incentives rather than deliberate generational favoritism.
The result can become self-reinforcing. Asset owners benefit from policies that preserve asset values, those rising values increase wealth, and greater wealth can increase the ability to participate in future policy debates. Younger households trying to enter those same markets may experience the system very differently.
Corporate Leadership Has the Same Age Dynamic
The private sector reflects many of the same forces. Corporate leadership tends to reward experience because managing large organizations requires knowledge of finance, operations, regulation, investors, and employees. That naturally favors executives who have spent decades building careers.
In 2026, Fortune reported that 42% of CEOs in a sample of large companies were at least 60 years old, with an average CEO age of 59. A separate analysis found that roughly 41.5% of Russell 3000 CEOs were 60 or older, up from 35.1% in 2017.
Yet corporate leadership may already be beginning to turn over. First-time CEOs appointed in 2025 averaged 54.4 years old, down from 55.8 a year earlier, and only 18% of newly appointed CEOs were age 60 or older. That suggests generational change can occur gradually through succession rather than through any abrupt break.
Longevity Allows Powerful People to Stay Powerful Longer
One reason leadership is older today is simply that people live and work longer. Improvements in medicine, safer workplaces, and higher living standards have allowed many people to remain professionally active well beyond the ages at which previous generations retired. Senior executives and politicians who remain healthy can continue operating into their 70s or 80s.
But longevity itself is unequal. A landmark U.S. study found that life expectancy at age 40 differed by roughly 14.6 years between men in the top and bottom 1% of the income distribution, and by about 10.1 years among women. More recent research continues to find meaningful income-related differences in life expectancy.
That creates an important connection between wealth and influence. People with greater economic resources are not only more likely to accumulate assets; on average, they may also have more healthy years available to remain involved in business, politics, investing, and civic life.
The Technology Story Is More Complicated Than “Boomers Built Everything”
Technology is often used as an example of older generations benefiting from being born at exactly the right time. There is some truth to the broader idea that historical timing creates opportunity, but individual examples need care. Google founders Larry Page and Sergey Brin, for instance, were both born in 1973, placing them firmly in Generation X rather than the baby boom.
Their timing was still extraordinary. They were graduate students at Stanford just as the commercial internet was expanding rapidly, allowing them to build Google in an environment where search technology was still immature and the market was far less crowded than it would become later. Opportunity was created not simply by their age but by being technically prepared at the moment a new technology emerged.
The same pattern has repeated across economic history. Railroad fortunes, automobile fortunes, computer fortunes, internet fortunes, and artificial intelligence fortunes all depend partly on entrepreneurs being positioned correctly when a new technological platform becomes economically important. Talent matters, but timing matters too.
Being Born Into the Right Era Can Create Enormous Advantages
Generational wealth differences often look like evidence that one generation made better financial choices than another. Some of the difference is behavioral, but much of it reflects the economic environment people encountered. Someone buying a house before decades of appreciation experienced a very different wealth-building path from someone attempting the same purchase after prices had already risen.
The same applies to stocks, education costs, interest rates, pensions, and wages. Baby boomers entered adulthood during a period when defined-benefit pensions were more common, housing was generally cheaper relative to income in many markets, and U.S. economic growth was strong. Younger generations gained advantages of their own, including access to technology, low-cost investing, remote work, and entirely new industries.
Generational comparisons become misleading when luck is ignored. People make decisions within the opportunities and constraints available at the time. A generation can benefit from economic conditions without having intentionally designed those conditions for itself.
Older Leaders Do Not Necessarily Pursue “Older” Policies
It is tempting to assume that older politicians automatically favor policies benefiting older voters or that younger politicians naturally support younger generations. Reality is far less predictable. Political preferences reflect party, ideology, geography, income, education, and constituency interests in addition to age.
The same principle applies to corporate leadership. An older CEO can aggressively invest in artificial intelligence and new technology, while a younger executive can run an extremely conservative organization. Age may shape experience, but it does not determine policy or management philosophy.
This distinction matters because criticism of aging leadership can easily slide into assumptions about competence or motivation that the evidence does not support. The more useful question is whether institutions provide enough pathways for new people and new ideas to compete for influence.
Congress Is Already Beginning to Get Slightly Younger
The generational turnover is not entirely hypothetical. Pew found that the 119th Congress was somewhat younger than recent Congresses. The median age of House members fell to 57.5, while the Senate median fell to 64.7 after several older members retired or left office.
Generation X is now the largest generational group in the House, while baby boomers remain much more dominant in the Senate. That distinction makes sense because Senate careers often begin later and last longer, while House elections create more frequent opportunities for generational turnover.
The process will likely continue incrementally. New generations do not suddenly inherit every institution at once. Leadership changes as individual executives retire, elected officials leave office, businesses transfer ownership, and voters select different candidates.
Corporate America Faces Its Own Succession Wave
A similar transition could develop across large companies. With a large share of current CEOs and CFOs approaching traditional retirement ages, some analysts expect a significant succession wave during the next decade. Fortune reported that one analysis places a peak departure window for senior corporate leaders between 2029 and 2034.
That transition could bring different management styles, technology preferences, workplace policies, and attitudes toward risk. Younger executives who spent their careers with cloud computing, social media, remote work, and artificial intelligence may approach organizations differently from leaders who learned management before those systems existed.
The outcome is not automatically better or worse. Succession creates opportunities for change, but it can also remove institutional knowledge that took decades to build. Companies that manage the transition well will need to balance new ideas with continuity.
The Biggest Transition May Be Wealth, Not Jobs
Leadership titles are only one part of generational power. The larger transition involves ownership. Older Americans control enormous amounts of real estate, retirement assets, stocks, and private businesses, much of which will eventually be transferred through inheritance, charitable gifts, or asset sales.
Federal Reserve data make clear how strongly household wealth is concentrated among older families and higher-wealth households. The oldest households saw especially large gains in the most recent Survey of Consumer Finances, while families younger than 35 experienced declines in median net worth between 2022 and 2025.
As those assets transfer, economic influence will transfer with them. The younger generations receiving businesses, homes, investment accounts, and capital will have greater ability to shape investment, entrepreneurship, philanthropy, and politics. The process will take decades rather than happen in one dramatic moment.
Younger Generations Will Not Inherit Wealth Equally
Talk of a generational wealth transfer can create the impression that younger Americans will broadly become wealthy as their parents age. In reality, inherited wealth will be distributed very unevenly because current wealth is already highly concentrated. Families without substantial assets cannot transfer what they do not own.
The Federal Reserve’s distributional accounts show that stocks, business ownership, and other financial assets remain heavily concentrated toward the top of the wealth distribution. That means the coming transfer could reinforce existing inequality even while moving assets from older to younger people.
Age and wealth therefore should not be treated as interchangeable. There are wealthy boomers and financially struggling boomers, just as there are wealthy millennials and millennials with little accumulated wealth. Generational averages can reveal broad economic patterns without describing every person inside the generation.
Longer Lives Are Delaying the Transfer
The timing of the wealth transition is also changing because people are living longer and retaining assets later into life. A household that once might have transferred wealth in its 70s may now retain those assets well into its 80s or 90s. Adult children can therefore receive inheritances much later than expected.
That has practical implications. Someone receiving a large inheritance at 60 may already own a home and be approaching retirement, meaning the money does relatively little to help with earlier milestones such as buying a first house or raising children. The timing of inheritance can therefore reinforce age-related wealth concentration even when assets eventually pass to the next generation.
Longer lifespans also mean older owners remain active in businesses and investment decisions longer. That can slow generational turnover even while providing continuity inside companies and families.
Power Will Shift, but Not Simply From “Old” to “Young”
Eventually every generation gives way to another. Baby boomers are already retiring from corporate leadership, selling businesses, leaving elected office, and transferring assets. Generation X is moving deeper into senior management and politics, while millennials increasingly occupy leadership positions of their own.
But the next power structure will not simply become younger and more equal. Wealth, education, family background, and professional networks will continue determining who gains access to influential positions. The children of wealthy households may inherit not only money but also relationships, education, businesses, and investment opportunities.
Age turnover therefore does not automatically solve economic concentration. It can change who controls institutions without fundamentally changing how access to power works.
The Real Story Is How Long It Takes to Build Influence
The aging of leadership is partly a demographic story, but it is also a story about how modern institutions distribute power. Political careers reward seniority, corporations reward experience, and financial markets reward decades of compounding. Those systems naturally create leaders and asset owners who are older than the population overall.
That is not automatically a flaw. Experience has value, and decades of investment should produce accumulated wealth. Problems arise when the pathways into leadership, homeownership, entrepreneurship, or asset ownership become too narrow for younger people to follow the same path.
A healthy transition does not require pushing older people out simply because of age. It requires making sure younger generations have realistic ways to build wealth, enter institutions, challenge incumbents, and eventually exercise influence of their own.
America Is Entering a Generational Handoff
The economic and political influence accumulated by baby boomers will not disappear. Much of it will be transferred—to heirs, charities, buyers of businesses, younger executives, and new political leaders. That makes the next several decades less a story about one generation losing power than about how that power is redistributed.
The change is already visible. Congress has become somewhat younger, incoming CEOs are younger than many incumbents, and leadership transitions are accelerating across businesses. At the same time, older households continue to hold enormous amounts of wealth and benefit from decades of asset appreciation.
The central question is not whether older people have too much influence simply because they are old. It is whether the economic system gives each new generation a credible path to build the assets, experience, and institutions necessary to gain influence over time. The generational handoff is inevitable. What matters is who is positioned to receive it.