Retirement Planning Should Start With Your Dreams, Not Your Account Balance
Retirement planning often begins with numbers: how much you have saved, how much you can withdraw, and whether the portfolio will last 30 years. Those calculations are essential, but they can still produce a disappointing retirement if no one has asked the bigger question of what the money is supposed to make possible. A strong financial plan should not simply prove that you can stop working; it should help you build a life you are excited to live.
That means starting with dreams before spreadsheets. Travel, time with family, charitable giving, a move to a new city, helping grandchildren, or finally pursuing a long-delayed hobby can all shape how much money is needed and when it should be spent. Retirement becomes more meaningful when those goals are treated as part of the plan rather than optional extras added after the math is finished.
Start With the Life You Want to Build
One of the most useful retirement questions is also one of the least financial: what would an ideal year actually look like? Instead of answering with broad ideas such as “travel more” or “spend time with family,” retirees should become specific enough that those goals can be planned and funded.
That could mean spending a month in Europe every other summer, paying for an annual family vacation, relocating closer to grandchildren, or buying season tickets for something that has always mattered. Another retiree may want to volunteer, start a small business, support a favorite charity, or spend more time outdoors. Those details help transform an abstract retirement into a life that can actually be designed.
The point is not to create an expensive wish list. It is to identify what matters most before deciding how the money should be allocated. Without that step, retirees can end up optimizing a portfolio for a life they never actually wanted.
Big Dreams Can Make Financial Planning More Useful
Dreaming bigger can sound irresponsible in a financial-planning conversation, but it can actually make the planning more useful. A modest plan built around vague goals may be technically successful while still leaving money underused and experiences repeatedly postponed.
Specific goals create something to plan toward. If a couple wants to spend $20,000 a year traveling for the first 10 years of retirement, the portfolio can be tested against that spending. If they want to help children with home purchases or contribute to grandchildren’s education, those amounts can be modeled as deliberate goals instead of unexpected withdrawals.
That creates a much better decision framework. Instead of asking whether a purchase is “too expensive,” the household can ask whether it fits within the priorities already established and what would need to change elsewhere to make it work.
Build a Retirement Vision Board
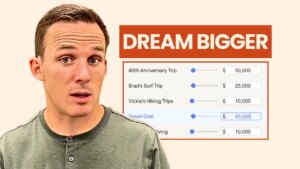
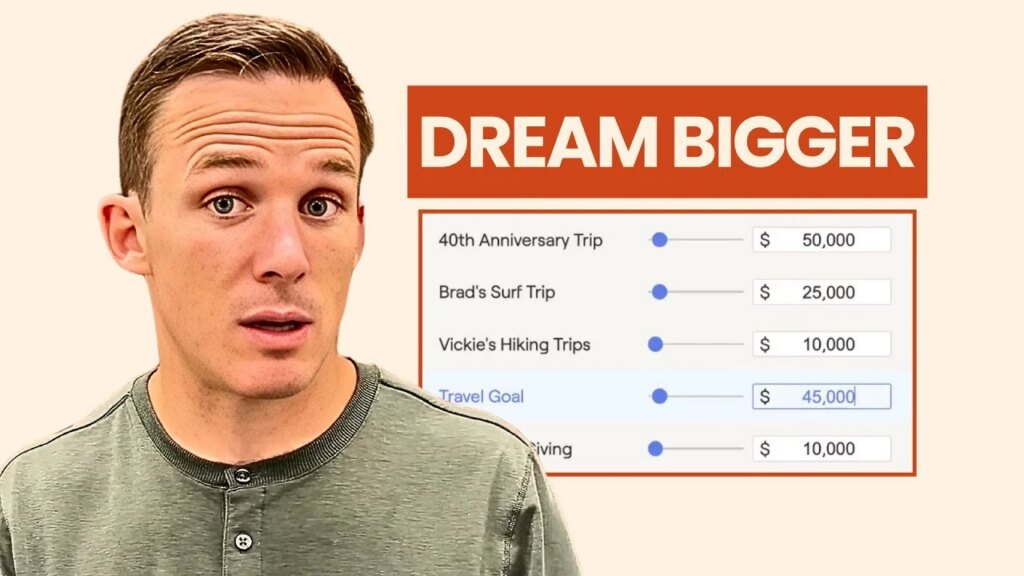
A retirement vision board does not need to be literal, but the concept is useful. Retirees can organize goals into categories such as experiences, family, housing, giving, health, and legacy, then assign rough timing and cost estimates to each one.
Some goals may happen every year, such as travel or charitable giving. Others may occur once, such as buying a second home, renovating a house, paying for a wedding, or taking a major family trip. Putting those goals in one place makes it easier to see how they compete for the same dollars.
This process also helps expose priorities. If a retiree would rather spend $15,000 on travel every year than leave another $300,000 to heirs, the investment and withdrawal strategy should reflect that preference. If preserving wealth for children is the highest priority, discretionary spending may need to be more conservative.
The Financial Plan Should Follow the Goals
Once the goals are clear, the numbers become more meaningful. Social Security, pensions, investment accounts, cash, and real estate can then be organized around the actual lifestyle the retiree wants to support.
A household expecting $90,000 of annual core expenses and another $25,000 for travel has a different cash-flow need from one spending $70,000 with few discretionary goals. The investment strategy, withdrawal rate, and timing of Social Security should therefore be tied to those specific needs rather than generic retirement rules.
This is where retirement planning becomes personal. Two couples with identical portfolios can make completely different decisions because one values experiences and family support while the other prioritizes leaving a large estate. Neither approach is automatically better if the plan is aligned with what matters to the people actually living it.
Brad and Vicki Show Why Priorities Matter
Consider Brad and Vicki, a couple with cash, retirement accounts, property, and several lifestyle goals. Their dreams include travel, family events, and eventually downsizing, which means their financial plan needs to account for both ongoing expenses and larger one-time decisions.
A traditional retirement model might simply ask whether their assets can support annual spending. A more useful plan would separate core living costs from the goals that make retirement meaningful, then determine how much each goal can receive without weakening long-term security.
If the plan becomes tight, the answer does not have to be abandoning the dream. Brad and Vicki might delay a major trip, reduce its cost, sell a larger home sooner, or shift spending from one category to another. Flexibility allows the goals to remain while the timing or scale changes.
Flexibility Can Be More Valuable Than Perfection
Retirement plans often fail because people assume every expense and market return will happen exactly as modeled. Real life rarely cooperates, so flexibility should be built into the plan from the beginning.
A couple might travel heavily in the first decade and reduce those expenses later. A home renovation could be delayed after a weak market year, while a strong year might create room for extra gifting or a larger vacation. Downsizing can also release home equity and lower ongoing costs if the household decides the current house no longer fits the lifestyle.
Those adjustments do not mean the plan failed. They are evidence that the plan is working as intended by adapting to changing circumstances instead of forcing the household to follow assumptions made years earlier.
Priorities Make Trade-Offs Easier
Every retirement plan eventually faces trade-offs. Few households can spend without limits, even when they have accumulated substantial wealth, so the question becomes which goals deserve priority.
A retiree may have enough to fund either a second home or a larger travel budget, but not both comfortably. Another household may need to choose between helping adult children now and preserving more for an eventual inheritance. Those decisions become easier when priorities have already been discussed openly.
Money decisions are much harder when the household has never agreed on what matters most. A clear hierarchy of goals turns financial planning from a series of restrictions into a way of deciding which experiences and values deserve the most resources.
Downsizing Can Be a Lifestyle Decision, Not Just a Financial One
Housing is one area where life goals and financial planning often intersect. Downsizing can lower property taxes, maintenance, insurance, and utility expenses while releasing home equity for other priorities.
But the financial benefit should not automatically drive the decision. A smaller home may be less appealing if it means leaving friends, family, familiar doctors, or a community that provides purpose and connection.
The right housing decision is therefore not simply the one that produces the highest ending portfolio balance. It is the one that gives the household enough financial flexibility while still supporting the life they want to live.
Family Support Should Be Intentional
Many retirees want to help children or grandchildren, but those gifts should be included in the plan rather than handled impulsively. Paying for education, helping with a down payment, or funding a family trip can be meaningful uses of wealth when they fit comfortably within the broader retirement strategy.
Planning those gifts in advance also reduces uncertainty. Retirees can determine how much they are willing to give, when the money is most useful, and whether the gift should come from cash, investments, or another asset.
That creates a healthier balance between generosity and security. Helping family can be part of the retirement dream without becoming an obligation that eventually limits the retiree’s own lifestyle.
Retirement Success Is Not the Largest Ending Balance
Financial planning software often measures success by whether the portfolio survives to a certain age. That is important, but it is not the same as measuring whether the retirement itself was successful.
A retiree who reaches age 95 with a very large portfolio but repeatedly postponed meaningful experiences may have managed money efficiently without necessarily using it well. Another retiree who spends more on family, travel, and meaningful experiences while still maintaining financial security may achieve a better balance between preservation and enjoyment.
The objective should be enough wealth, not necessarily maximum wealth. Once long-term security is established, additional dollars should be evaluated based on what they can contribute to life rather than simply how large they can make the final account statement.
Give Yourself Permission to Dream Bigger
Many people spend their working lives being responsible with money, which can make it surprisingly difficult to begin spending in retirement. Decades of saving become habits, and retirees can feel guilty about large purchases even when the financial plan shows they are affordable.
That is where the planning process can become empowering. If the numbers show that a dream is sustainable, retirees may need permission to actually pursue it rather than continuously moving the goal farther into the future.
Dreaming big does not mean ignoring risk or spending recklessly. It means identifying what would make retirement memorable, then building a financial structure capable of supporting it.
The purpose of a retirement plan is not simply to avoid running out of money. It is to make sure the money you spent decades accumulating helps create a life worth retiring to.
You should always consult a financial, tax, or legal professional familiar about your unique circumstances before making any financial decisions. This material is intended for educational purposes only. Nothing in this material constitutes a solicitation for the sale or purchase of any securities. Any mentioned rates of return are historical or hypothetical in nature and are not a guarantee of future returns.
Past performance does not guarantee future performance. Future returns may be lower or higher. Investments involve risk. Investment values will fluctuate with market conditions, and security positions, when sold, may be worth less or more than their original cost.