Buy Now, Pay Later Makes Purchases Feel Cheaper. That Is Exactly Why It Can Be Dangerous
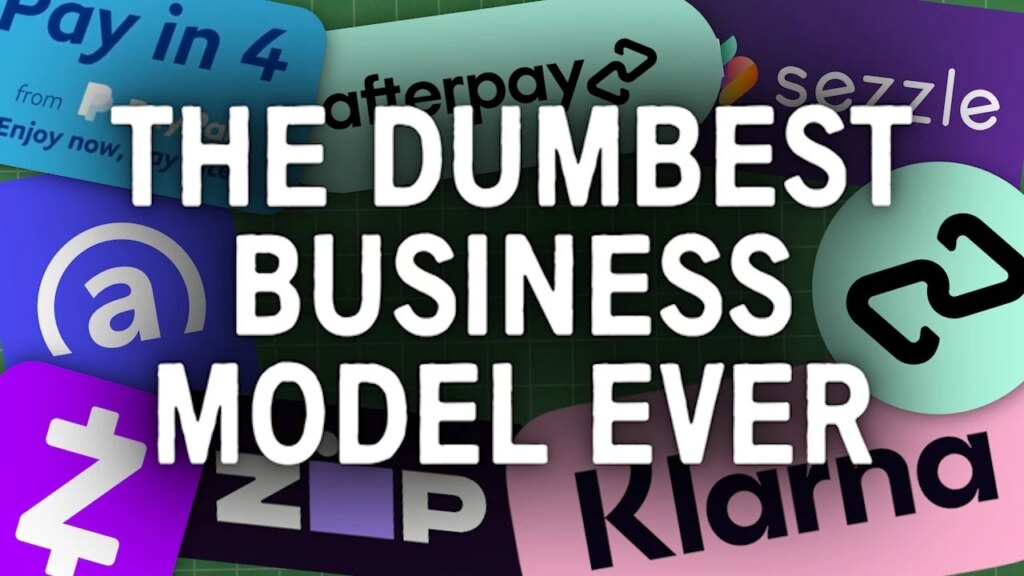
Buy now, pay later has transformed the checkout page into a lending decision. Instead of paying $200 for a pair of shoes, a shopper may be offered four payments of $50, often with no interest and almost no friction between wanting the product and financing it. That convenience has helped BNPL become one of the fastest-growing forms of short-term consumer credit, particularly among shoppers who prefer not to use a traditional credit card.
The appeal is obvious, but so is the risk. Breaking a purchase into smaller installments can make the item feel more affordable even though its total price has not changed, and consumers can accumulate several of these obligations at once without seeing them presented on a single monthly statement. The real danger is therefore not necessarily one large loan, but a collection of small loans that quietly claim future paychecks before the consumer realizes how much has already been committed.
BNPL Has Grown Quickly
The Consumer Financial Protection Bureau’s most recent market study found that six large BNPL providers served a combined 53.6 million users in 2023. The number of loans issued by those firms increased 23% from 2022, while inflation-adjusted dollar volume increased 26%. Users also borrowed more frequently, averaging 6.3 loans per lender during the year, up from 5.7 a year earlier.
Those figures are significant, but they do not support claims that Americans have accumulated more than half a trillion dollars of BNPL debt. The market is difficult to measure precisely because many traditional pay-in-four loans historically have not been consistently reported to the major credit bureaus. That means policymakers and lenders have had less visibility into total BNPL obligations than they have with credit cards, mortgages or auto loans.
The reporting gap is one of the most important differences between BNPL and traditional consumer credit. A borrower may appear to have relatively little conventional debt while simultaneously owing money to several BNPL providers. That makes it harder for lenders to understand the borrower’s complete obligations and harder for consumers to see their own debt picture in one place.
Small Loans Can Become a Large Monthly Obligation
A single $40 installment may not seem financially important. The problem begins when the same consumer is making $40 payments for clothing, $60 payments for electronics, $25 payments for furniture and another series of payments for travel or groceries. Each purchase may feel manageable independently while the total amount due over the next several paychecks becomes increasingly difficult to absorb.
CFPB research found that roughly 63% of BNPL borrowers had multiple simultaneous BNPL loans at some point during 2021 or 2022. About one-third had active loans with more than one BNPL provider at the same time, which matters because one company may not know what the consumer already owes to another.
The same research found that BNPL borrowers were more likely to carry balances across other forms of unsecured credit as well, including credit cards, personal loans and retail loans. That does not prove BNPL causes broader financial trouble, because people already under financial pressure may simply be more likely to use the product. It does show, however, that BNPL should not automatically be viewed as a substitute for other debt when many consumers are using it alongside other borrowing.
The Product Works Because It Changes How People See the Price
BNPL is powerful partly because it changes the way a purchase is framed. A $400 product can suddenly appear as four payments of $100, shifting attention away from the full price and toward whether the next installment fits into the current budget. That psychological difference can affect how much shoppers are willing to spend.
Academic research published in the Journal of Retailing found that customers adopting BNPL spent about 6.4% more online than comparable customers using traditional payment methods. Another study found that the installment format itself can reduce consumers’ perception of how expensive a purchase feels, leading them to spend more than they otherwise would.
Research from the National Bureau of Economic Research found an even larger effect in a merchant setting, where offering BNPL increased sales by about 20%. Conversion rates rose from roughly 70% to 80%, and customers purchased higher-value products when the financing option was available. That helps explain why retailers are willing to pay meaningful fees for BNPL even when customers pay little or no interest.
Merchants Pay Because BNPL Can Increase Sales
BNPL companies do not need every customer to pay interest because merchants often pay for access to the financing service. Payment processor Stripe says BNPL merchant commissions commonly fall around 2% to 8% of the transaction amount, substantially higher than the cost many merchants associate with ordinary card acceptance.
Retailers accept those fees because the financing can increase conversion rates and average order values. A customer who might abandon a $600 purchase may complete it when the checkout page reframes the cost as several smaller payments, making the merchant willing to sacrifice some margin to secure the sale. The economics can work particularly well for higher-margin products where the additional revenue exceeds the financing fee.
Those costs do not necessarily appear as a separate BNPL surcharge for consumers, but they still become part of the merchant’s overall economics. Retailers ultimately have to recover payment-processing, financing and marketing costs somewhere, which can influence pricing across the business even when the BNPL user sees a 0% financing offer.
Zero Interest Does Not Mean Zero Risk
One reason BNPL feels safer than a credit card is that many pay-in-four products charge no interest when payments are made on time. That can make them useful for consumers who have the money but prefer to spread a purchase across several pay periods. The financial risk emerges when BNPL becomes a way to purchase items that would otherwise be unaffordable.
Some providers charge late fees when payments are missed, and consumers can also incur overdraft or nonsufficient-funds charges from their bank if an automatic BNPL payment hits an account without enough money. An unpaid BNPL balance may eventually be sent to collections, and negative information can affect credit if it is reported.
The absence of a traditional interest charge can therefore create a false sense that the transaction is not really debt. It is still an obligation against future income, and the consumer still loses financial flexibility until the installments are paid.
BNPL Borrowers Often Already Carry Other Debt
The broader debt profile of BNPL users is another reason the market deserves attention. CFPB research found that BNPL borrowers were more likely than nonusers to carry balances on other forms of unsecured credit and that many originated multiple BNPL loans during the same period. The product is therefore not always replacing expensive credit-card borrowing; in some cases it is being added on top of it.
That distinction matters because a consumer can manage one short-term installment loan easily while struggling with several overlapping obligations. A credit card at least consolidates purchases onto one statement with one minimum payment, while BNPL payments may arrive on different days from different providers. The fragmentation can make household cash-flow management more complicated even when the total amount borrowed remains relatively modest.
Recent research has also linked frequent BNPL use with financial fragility, including limited emergency savings and irregular income. That does not establish that BNPL creates financial insecurity, but it suggests financially stressed households may be especially attracted to the product because it allows today’s purchase to be pushed into tomorrow’s budget.
Klarna Shows the Business Model Can Still Make Money
The outline’s claim that BNPL firms broadly cannot become profitable also needs more nuance. Klarna, one of the industry’s best-known companies, reported a $9 million profit in the second quarter of 2026, reversing a $53 million loss a year earlier. Revenue rose 27% to about $1.04 billion, while gross merchandise volume increased 18% to $36.6 billion.
That does not mean the business is easy or that every BNPL provider will succeed. Klarna also reduced its full-year growth outlook because of weaker retail conditions in Germany, showing how dependent the model remains on consumer spending and merchant transaction volume. Companies that rely heavily on payment activity can come under pressure quickly when shoppers pull back.
The industry’s economics are therefore more complicated than simply saying BNPL is unprofitable. Some companies may struggle with losses while others improve margins as they gain scale, expand into advertising or banking products, and increase transaction volume. The larger question is whether long-term profitability can coexist with responsible underwriting and meaningful consumer protections.
BNPL Regulation Has Been Uneven
Traditional credit cards operate under a mature regulatory structure that includes detailed disclosure, billing-error and consumer-protection requirements. BNPL developed much more recently, and policymakers have spent years debating which existing lending rules should apply to a product that behaves partly like an installment loan and partly like a payment method.
The CFPB attempted in 2024 to clarify that certain BNPL lenders should provide protections similar to those required of credit-card issuers, including dispute and refund rights. The agency withdrew that interpretive guidance in May 2025, leaving the federal regulatory framework less settled than it had briefly appeared.
That does not mean BNPL companies operate without regulation. Federal and state lending, consumer-protection and fair-lending laws can still apply depending on the structure of the product, and Regulation Z broadly governs many types of consumer credit. The important point is that BNPL developed faster than the regulatory system’s ability to create a clear, uniform framework specifically tailored to the product.
BNPL Is Not the Same as Payday Lending
Comparing BNPL directly with payday loans can also be misleading. Traditional pay-in-four BNPL products often charge no interest, while payday loans can carry extremely high effective annual borrowing costs and frequently rely on repeated renewals or replacement loans. The financial structures are therefore materially different.
There are similarities worth watching, particularly when consumers repeatedly borrow to cover ordinary expenses or use new credit because previous obligations have already reduced available cash. Both products can become problematic when short-term borrowing turns into a recurring way of managing an ongoing budget deficit. But describing BNPL as simply another form of payday lending ignores meaningful differences in pricing, underwriting and repayment structure.
The better comparison is behavioral rather than contractual. Both forms of credit can make today’s purchase or expense easier while reducing the amount of tomorrow’s income that remains available for everything else.
Credit Cards Can Be Worse—and Sometimes Better
Credit cards are hardly a perfect alternative. Revolving balances can carry high interest rates for years, minimum payments can prolong debt and large credit lines can encourage consumers to spend beyond their means. Someone who uses BNPL responsibly and pays every installment on time may pay substantially less than someone who carries the same purchase on a high-interest credit card.
Credit cards nevertheless offer advantages that BNPL has not always matched consistently. They typically consolidate spending into one statement, have well-established dispute processes and are deeply integrated into the consumer-reporting system. A lender evaluating a new loan can generally see a consumer’s reported credit-card obligations in a way that historically has not been possible with every BNPL loan.
The question is therefore not whether BNPL or credit cards are universally better. It is whether the consumer understands how much is owed, what the borrowing costs and whether the purchase would still make sense if the full price appeared on the checkout screen.
The Biggest Risk Is Making Expensive Purchases Feel Small
The genius of BNPL is the same thing that makes it risky. It transforms one large financial decision into several much smaller decisions, which can make spending feel painless even when the total purchase remains expensive.
A $1,000 television is still a $1,000 television whether it is purchased with cash, a credit card or four payments of $250. Splitting the cost changes when the money leaves the bank account, but it does not reduce the economic cost of the purchase.
That difference is easy to overlook when every online checkout page emphasizes the installment amount instead of the full obligation. For shoppers already managing several loans, credit-card bills and living expenses, another small payment can be exactly what pushes the monthly budget from manageable to strained.
A Simple Rule Can Prevent Most BNPL Problems
BNPL can be useful when the consumer already has the cash available and is using installments for convenience rather than affordability. In that situation, the payment plan changes timing without fundamentally changing whether the purchase fits into the budget. The risk rises sharply when the consumer needs BNPL in order to make the purchase possible.
A useful test is to look at the full price instead of the installment. If spending $400 today would feel unaffordable, converting the purchase into four $100 payments does not necessarily make it affordable; it simply distributes the strain across future paychecks. Consumers should also total every outstanding BNPL payment before taking on another one rather than evaluating each checkout in isolation.
The most important question is therefore not whether the first installment fits. It is how much future income has already been promised to purchases made in the past.
BNPL Is Credit Even When It Doesn’t Feel Like Credit
Buy now, pay later has succeeded because it removes nearly every emotional cue associated with borrowing. There may be no plastic card, no obvious interest charge and no large loan application, while approval can occur within seconds at the exact moment someone is deciding whether to buy.
That frictionless experience can be genuinely useful, and most BNPL borrowers successfully repay their loans. CFPB data show falling late-fee incidence and declining charge-off rates among the large providers it studied, evidence that the market is not simply a collection of failing loans.
The deeper concern is behavioral. A financial product does not need a high default rate to encourage consumers to spend more than they otherwise would, and research increasingly shows that installment framing can affect purchasing decisions. BNPL’s success comes partly from making the cost of a purchase feel smaller.
That is exactly why consumers should treat it like any other debt.