How Small Retirement Changes Can Dramatically Improve Your Plan
Retirement planning is rarely about finding one perfect withdrawal rate or following a generic rule. A strong plan starts with understanding how much you want to spend, where your income will come from, how your investments are positioned, and how those pieces change over time. For one couple approaching retirement, the difference between a fragile plan and a much stronger one came from making several relatively modest adjustments.
The couple wants to retire at 65 and spend about $14,000 per month, including roughly $4,000 for travel. That level of spending is intentionally high during the early retirement years, when they expect to travel more and enjoy the lifestyle they worked to build. Over time, those travel expenses are expected to decline, which is an important distinction because retirement spending rarely remains perfectly flat for decades.
Start With Realistic Spending
One of the biggest retirement-planning mistakes is assuming every expense will rise at the same rate forever. Some costs, including healthcare, may increase significantly, while travel and entertainment often decline later in retirement. Modeling those expenses separately can produce a much more realistic picture of how much money the portfolio actually needs to support.
In this case, the couple’s initial retirement plan produced a relatively low probability of long-term success. Their early withdrawal needs were substantial, and without adjustments, the portfolio risked becoming depleted too quickly. Rather than immediately concluding that retirement was unaffordable, the analysis looked at where the plan could be improved.
Income Timing Changes the Math
The couple still expects salary income for the next three years, followed eventually by Social Security beginning at age 70. That creates a period between retirement and Social Security when the portfolio must provide a larger share of their income. Healthcare expenses during those years must also be considered, including Medicare premiums and other out-of-pocket costs later in retirement.
That timing matters because a retirement portfolio does not experience the same level of pressure every year. Early retirement may require relatively large withdrawals, while Social Security and reduced discretionary spending can lower the portfolio’s burden later. A good plan accounts for those changing income and spending patterns rather than assuming retirement looks identical from age 65 through age 95.
Portfolio Allocation Needs to Match the Plan
The original portfolio allocation was relatively moderate, but the analysis showed that a greater allocation toward growth assets could improve the long-term outlook. That does not mean every retiree should simply own more stocks. Asset allocation needs to reflect both the amount of growth required and the investor’s ability to tolerate market declines.
For this couple, the portfolio needed enough growth potential to support decades of withdrawals. Remaining too conservative could create its own risk if returns were insufficient to keep pace with inflation and spending. The appropriate allocation therefore had to balance short-term volatility with the longer-term danger of the portfolio failing to grow enough.
Roth Conversions Can Improve Long-Term Results
Tax planning also played an important role. The years after retirement but before Social Security and required distributions can create an opportunity to move money from traditional retirement accounts into Roth accounts. The strategy modeled systematic conversions while keeping taxable income within a targeted range.
The plan considered conversions up to roughly the 12% tax bracket when appropriate. Paying some tax earlier can reduce future required minimum distributions, increase the amount held in tax-free accounts, and potentially leave more money available for heirs. The goal is not simply to minimize this year’s taxes, but to reduce total tax leakage across the entire retirement.
Small Changes Can Produce a Big Improvement
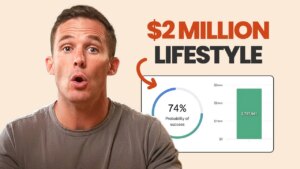
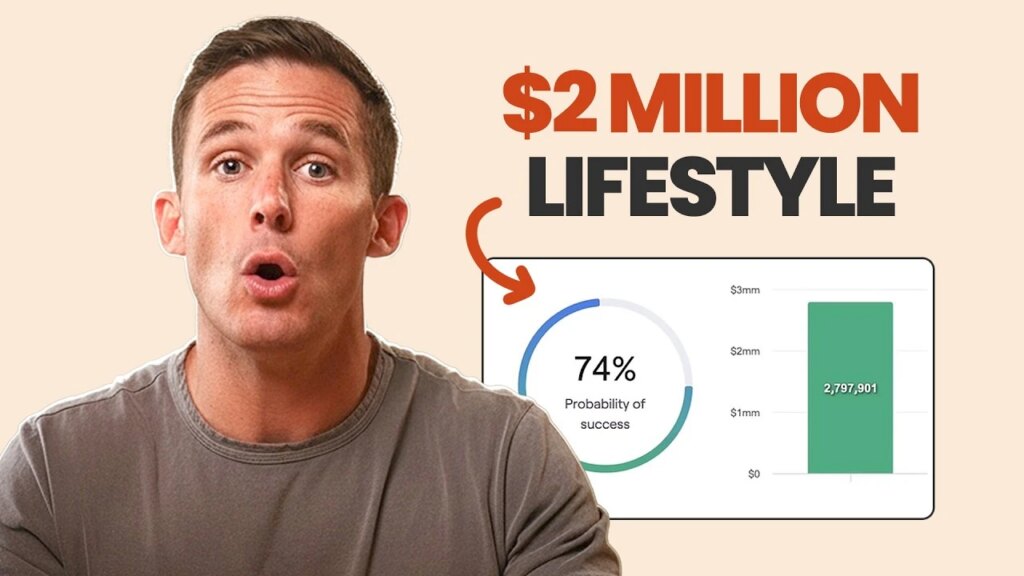
The most important result was how much the plan improved without requiring the couple to completely change their retirement goals. The original assumptions produced only about a 32% probability of success. After adjusting spending assumptions, portfolio allocation, tax strategy, and other variables, the modeled probability increased to roughly 74%.
That does not mean 74% is automatically the correct target for every retiree. It shows why retirement planning should be an iterative process. Small decisions involving when expenses occur, how assets are invested, and when taxable income is recognized can compound into a dramatically different long-term outcome.
Future lifestyle changes can improve the plan even further. Downsizing to a less expensive home, reducing travel later in life, or making other adjustments can lower future expenses and increase financial flexibility. Those possibilities should not necessarily be treated as sacrifices, but as potential backup strategies that can be incorporated if circumstances change.
The broader lesson is that retirement plans should be personalized and updated regularly. Generic withdrawal rules can provide a useful starting point, but they cannot account for an individual’s spending patterns, Social Security timing, taxes, housing decisions, portfolio allocation, and future lifestyle changes. A retirement that initially looks difficult may become much more achievable once those variables are modeled together and adjusted intentionally.
You should always consult a financial, tax, or legal professional familiar about your unique circumstances before making any financial decisions. This material is intended for educational purposes only. Nothing in this material constitutes a solicitation for the sale or purchase of any securities. Any mentioned rates of return are historical or hypothetical in nature and are not a guarantee of future returns.
Past performance does not guarantee future performance. Future returns may be lower or higher. Investments involve risk. Investment values will fluctuate with market conditions, and security positions, when sold, may be worth less or more than their original cost.