Medicare Costs More in 2026. Here’s How Income Can Make the Bill Even Higher
Medicare is often described as affordable health coverage for retirees, but the monthly bill can vary dramatically depending on income. In 2026, the standard Medicare Part B premium rose to $202.90 a month, up from $185 in 2025. For higher-income beneficiaries, however, income-related surcharges can push that monthly Part B premium as high as $689.90 before prescription coverage or supplemental insurance is added.
Those additional charges are known as the Income-Related Monthly Adjustment Amount, or IRMAA, and they affect both Medicare Part B and Part D. The rules can surprise retirees because Medicare generally determines the surcharge using tax information from two years earlier. Someone who retires and experiences a large income decline may therefore initially be charged based on a salary that no longer exists.
Understanding how Medicare is funded, how IRMAA works and when a surcharge can be appealed can prevent a costly retirement surprise.
Part A and Part B Are Funded Differently
Medicare Part A primarily covers inpatient hospital care, skilled nursing facility care, hospice and certain home health services. Workers help finance the program throughout their careers through the Medicare payroll tax. Employees generally pay 1.45% of wages for Medicare, with employers paying another 1.45%, while certain higher-income workers owe an additional Medicare tax.
That employment history is also why most retirees do not pay a monthly Part A premium. CMS says approximately 99% of Medicare beneficiaries receive premium-free Part A because they or a spouse accumulated at least 40 quarters of Medicare-covered employment. The Part A hospital deductible is $1,736 in 2026.
Part B operates differently. It covers services including physician visits, outpatient hospital care, durable medical equipment and certain home health services. Part B is funded primarily through beneficiary premiums and federal general revenues rather than solely through payroll taxes.
Beneficiary premiums are designed to cover about one-quarter of standard Part B program costs, with general federal revenues financing most of the remainder. Higher-income beneficiaries pay a larger percentage through IRMAA, which is why two retirees with identical Medicare coverage can have dramatically different monthly premiums.
The Standard Part B Premium Is $202.90 in 2026
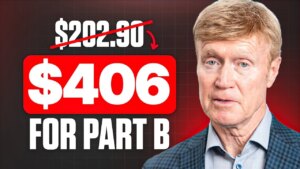
The standard monthly Part B premium increased by $17.90 in 2026 to $202.90. The annual Part B deductible also rose to $283 from $257 in 2025. CMS attributed the increases largely to projected changes in medical prices and expected utilization.
That means a beneficiary paying the standard premium will spend about $2,435 annually on Part B premiums alone. That figure does not include the Part B deductible, Medicare Supplement insurance, Medicare Advantage premiums, prescription drug coverage or other out-of-pocket health costs.
The premium increase also illustrates why health care inflation matters in retirement planning. Someone who enters retirement assuming today’s Medicare premium will remain relatively stable for the next 20 years may underestimate future expenses substantially.
IRMAA Can More Than Triple the Part B Premium
Most Medicare beneficiaries pay the standard $202.90 premium, but people above certain income thresholds pay more. For 2026, IRMAA begins when modified adjusted gross income exceeds $109,000 for an individual or $218,000 for a married couple filing jointly. CMS estimates that roughly 8% of people with Medicare Part B pay these income-related amounts.
The first IRMAA tier increases the monthly Part B premium to $284.10. Higher tiers increase the payment to $405.80, $527.50 and $649.20. At the highest 2026 bracket, individuals with MAGI of at least $500,000 and married couples filing jointly with at least $750,000 pay $689.90 per person each month.
For a married couple in the highest bracket, that means Part B alone can cost roughly $16,558 a year before adding Part D or supplemental coverage. The financial impact can therefore be meaningful even for households with substantial resources.
IRMAA is effectively structured so higher-income beneficiaries pay a greater share of the government’s estimated Part B costs. Rather than everyone paying the same subsidized premium, the percentage borne by beneficiaries increases as income rises.
Medicare Looks Back Two Years
One of the most frustrating aspects of IRMAA is the timing. Social Security generally uses modified adjusted gross income from the tax return filed two years before the Medicare premium year. For 2026 premiums, that normally means income reported for 2024.
That can create a mismatch for newly retired people. Someone might have earned $250,000 in 2024, retire in 2026 and suddenly live on $90,000 of annual income. Medicare may initially calculate the person’s 2026 premium using the much higher 2024 earnings.
Modified adjusted gross income for IRMAA purposes generally includes adjusted gross income plus tax-exempt interest. That means income from traditional retirement-account withdrawals, investment gains and other taxable sources can potentially move a retiree into a higher Medicare bracket.
This is why Medicare premium planning increasingly overlaps with tax planning. A large Roth conversion or substantial capital gain can increase income enough to trigger IRMAA two years later even though the transaction itself may have been financially sensible.
Part D Has Its Own IRMAA Charge
Higher-income retirees can also pay an IRMAA surcharge on Medicare Part D prescription drug coverage. Unlike Part B, there is no single standard Part D premium because beneficiaries choose among private drug plans with different prices.
For 2026, the Part D IRMAA surcharge begins at the same $109,000 individual and $218,000 married-filing-jointly thresholds used for Part B. The additional monthly amount ranges from $14.50 in the first income tier to $91 at the highest level. That surcharge is paid in addition to whatever premium the individual drug plan charges.
That means a high-income beneficiary can face increased costs on both sides simultaneously. A married couple can each owe elevated Part B premiums as well as separate Part D surcharges, making income management increasingly relevant as retirees approach Medicare.
It also means retirees should avoid assuming that finding a low-premium Part D plan eliminates Medicare’s prescription premium cost. IRMAA is separate from the insurer’s plan premium.
Retirement Can Give You Grounds to Reduce IRMAA
The two-year lookback would be particularly harsh if there were no way to account for a major income decline. Social Security therefore allows beneficiaries to request a new IRMAA determination after certain qualifying life-changing events.
There are eight recognized events: marriage, divorce or annulment, death of a spouse, stopping work, reducing work, loss of income-producing property beyond the person’s control, certain losses of pension income and certain employer settlement payments. A beneficiary whose income falls because of one of these events can use Form SSA-44 to request that Social Security use more recent income information.
Retirement is especially relevant because work stoppage is one of the qualifying events. If someone retires and household income drops substantially, the person may not have to wait two years for the old salary to disappear from the Medicare calculation.
Documentation matters. Social Security may require evidence of the event and the resulting income change, such as employer documentation showing that work ended or hours were reduced.
A Roth Conversion Isn’t an IRMAA Life-Changing Event
One important distinction is what does not qualify. A voluntary financial decision that raises or lowers income is not automatically an IRMAA life-changing event.
For example, a large Roth conversion can increase modified adjusted gross income and push someone into a higher IRMAA bracket two years later. The fact that income drops again the following year does not by itself provide grounds for an SSA-44 appeal. The Social Security Administration’s qualifying-event list is specific, and ordinary investment-income changes or voluntarily generated taxable income are not included.
That does not mean retirees should avoid Roth conversions. Paying taxes and possibly higher Medicare premiums now could still produce substantial lifetime tax savings. The important point is to model the Medicare cost alongside the tax benefit rather than discovering the surcharge afterward.
Someone considering a large conversion at 63 or 64 should therefore understand that the income could affect Medicare premiums once enrolled. The correct strategy depends on the amount converted, future tax rates, required minimum distributions and the size of any resulting IRMAA charge.
You Don’t Necessarily Have to Wait Until the Income Drop Is Over
The appeal timing is slightly more flexible than the outline suggests. The current SSA-44 allows someone who has had or anticipates having a qualifying life-changing event to report an income reduction associated with that event. The form can account for reductions that already occurred as well as anticipated reductions in the current or following year.
However, the beneficiary generally needs an IRMAA determination to challenge. Form SSA-44 itself says it may be used when the person has received notice that Part B or prescription-drug premiums include IRMAA and has experienced a life-changing event that could reduce it.
That makes preparation useful even before retirement. Someone expecting to stop working can estimate the new income level, collect appropriate documentation and understand the appeal procedure rather than beginning the process only after unexpectedly seeing a higher Medicare deduction.
Medicare Is Much Bigger Than the Monthly Premium
Another important correction involves the overall cost of Medicare. The program is far larger than simply multiplying the Part B premium by the number of beneficiaries.
CMS reports that Medicare covered about 69.3 million people in 2025 and spent just over $1.2 trillion during the year. Part B alone paid roughly $578 billion in net health benefits in 2025.
Those figures help explain why relatively modest percentage increases in medical costs can produce substantial changes in premiums and federal spending. Medicare combines beneficiary premiums, payroll-tax revenue and large transfers from the federal government’s general revenues to finance care for tens of millions of older and disabled Americans.
For retirees, however, the more relevant number remains the personal monthly premium. The government’s average cost of providing Medicare benefits is not the amount the typical person sees deducted from a Social Security check.
Tax Planning Can Become Medicare Planning
IRMAA creates a reason for retirees to look several years ahead when making tax decisions. Selling a highly appreciated investment, exercising stock compensation, completing a major Roth conversion or taking a large traditional IRA distribution can increase Medicare premiums two years later.
That does not necessarily make the transaction a mistake. Someone might willingly pay an additional few thousand dollars of Medicare premiums to complete a Roth conversion that produces much larger lifetime tax savings. The problem comes when IRMAA is ignored altogether.
Income thresholds also function like cliffs because moving slightly into the next bracket can increase the entire monthly surcharge. That makes year-end tax projections particularly useful for retirees whose income is near one of the boundaries.
The same planning can work in reverse. Charitable strategies, the timing of investment gains and careful retirement-account withdrawals may help control modified adjusted gross income when those decisions also make sense within the broader financial plan.
The Medicare Bill Is Partly a Tax-Planning Problem
For most retirees, the 2026 Medicare Part B premium is straightforward: $202.90 per month. But for higher-income households, that number can climb rapidly, with Part B reaching nearly $690 per person each month and Part D adding another surcharge.
The surprising part is that today’s Medicare premium can depend on financial decisions made two years ago. A retirement, Roth conversion, investment sale or unusual income year can therefore affect health-care costs long after the original transaction.
Fortunately, some retirees whose income falls because of a qualifying life-changing event can request a new determination rather than remaining stuck with a surcharge based on income they no longer earn. That makes understanding Form SSA-44 nearly as important as understanding the IRMAA brackets themselves.
Medicare premiums are not simply another fixed retirement expense. For many households, they are connected directly to income, tax strategy and the timing of retirement decisions.